Profit Loss SpreadsheetThe matched file, opened in Dallas
Dallas is where the spreadsheet is opened. The owner stays on the video call while each cleared mark is decided.
The Dallas practice opens the file
The practice is in Dallas, and a Texas owner still gets the month matched without the drive. On the video call we share the spreadsheet, we read the statement line by line, and the cleared column gets its yes or no before anyone hangs up.
Owners in Dallas and Fort Worth can feel as if a neighbor is on the other side of the same screen. For a reader farther out, the plain sentence is the one we mean. We are all Texans. There is no room of ours on your square, and the call will not pretend your street is one we walk. The match is still the Dallas practice, done on the day you already close.
A Hill Country bakery, a Gulf boat shop, and a Panhandle yard can each send the workbook they already keep. County lines do not rename the six columns. What does change is the Comptroller letter that sometimes lands after close, plus two Texas amounts the matched file has to park beside the profit cell. Collected sales tax is one. The revenue figure the franchise report will read is the other.
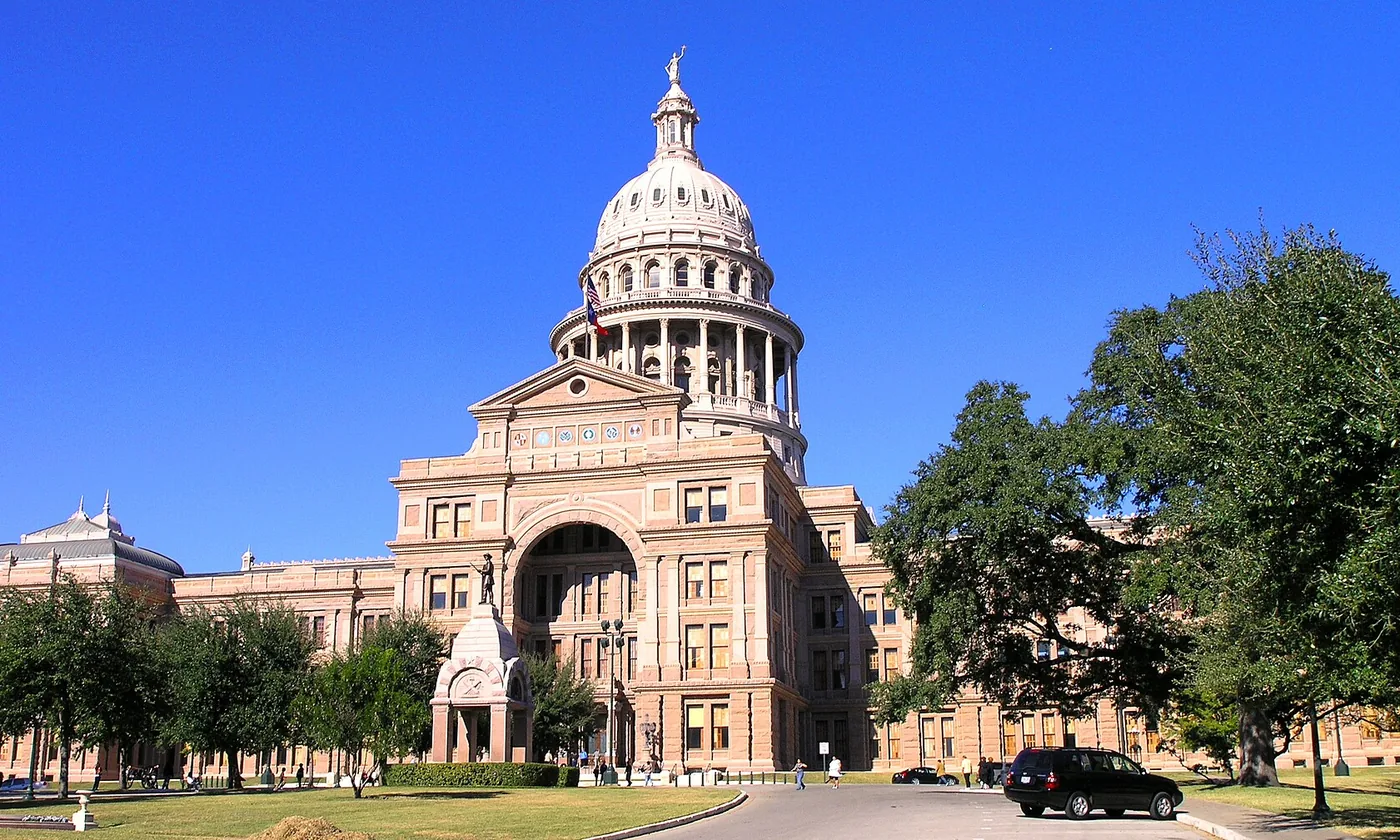
The picture above is the Texas State Capitol in Austin, photographed by Daniel Mayer and offered under CC BY-SA 3.0 on Wikimedia Commons. We cropped the frame. Visitors tie the franchise report to that dome. The spreadsheet work itself stays in the Dallas practice.

What the matched rows feed into the report
Texas prices the privilege of doing business through a company with the franchise tax, and Publication 98-806 is the Comptroller's plain account of who sends a report, which a spreadsheet owner should read before treating the profit cell as if it were that report, a list that takes in corporations, one-owner limited liability companies, series companies, partnerships, trusts, banks, S corporations, professional associations, and joint ventures.
Invoicing under a personal name, with no company ever formed, generally keeps a person off that filing list, and a partnership of human partners is generally off it as well unless the partnership carries limited liability, while examples of what counts as doing business in Texas are the ones Rule 3.586 supplies when Publication 98-806 sends a reader there.
Margin is the number the report is built on, and total revenue inside that margin begins with the federal revenue amounts after the exclusions in Tax Code section 171.1011. A matched spreadsheet is how those amounts stay honest. A loan deposit typed into sales makes the report tell a story the bank statement never lived. Cash moved to the owner and typed as an expense shrinks margin for a reason the shop did not earn. Cleared columns are the input. The franchise report should not be the first page where those mix-ups show up.
Four margin computations once the rows agree
When the long form is the one in front of you, the owner chooses a single computation and every member of a combined group has to share that choice, whether the choice is seventy percent of total revenue, or total revenue after goods-cost comes off, or total revenue after compensation comes off, or total revenue after the one-million-dollar subtraction the statute has carried since the opening of 2014, and the spreadsheet ought to show which of those four the cleared rows can actually carry.
What you spent to acquire or produce tangible goods, and real property, that you sell in the regular course is the ordinary meaning of the goods-cost computation, so a service shop with no goods rows should leave that spreadsheet column blank instead of inventing a figure, while the industry exceptions stay in section 171.1012 rather than getting flattened into a slogan here.
W-2 wages, cash paid to officers, directors, owners, partners, and employees, and net distributive income paid to a human owner all go into the compensation computation, each person only up to the cap for that report year, along with benefits the company may deduct such as health coverage, retirement, and workers' compensation, while 1099 labor and the payroll taxes the company itself pays stay outside that count, and the margin that remains is apportioned on gross receipts sourced to Texas.
A column heading belongs to one month, and the compensation cap belongs to one report year in the same way, so the 2026 and 2027 reports use a cap of 480,000 dollars a person while the 2024 and 2025 reports use a cap of 450,000 dollars a person, and a figure from the earlier pair of years does not get dropped into a sentence that is describing 2026.
No-tax line, rates, and the information report
Print the report year beside the revenue total in the spreadsheet, the way the Comptroller prints the no-tax threshold beside the year, because annualized total revenue at or under 2,650,000 dollars in 2026 or in 2027 means the franchise tax is not owed and the tax report is not the filing, while 2024 and 2025 used a line of 2,470,000 dollars, and even under the later rule the company still sends Form 05-102 as a public information report or Form 05-167 as an ownership information report unless the Comptroller's skip list already covers it.
An unfiled short report can cost the company the right to sue or to defend in a Texas court and can leave officers, directors, partners, members, or owners exposed on certain debts, which is the warning the Comptroller attaches to Tax Code sections 171.251, 171.2515, 171.252, and 171.255, whereas financial institutions stand apart from that warning under sections 171.259 and 171.260 and those two sections should stay in their own sentence on the file's cover note.
Each member of a combined group that was organized in Texas, and each member that has nexus, still sends its own information report in a year when no tax is due, the ownership detail on Form 05-167 stays confidential, Form 05-102 is signed by an officer or by another person the company authorized, and a registered-agent change belongs at the Secretary of State rather than on either of those reports, while officer changes after filing wait for the following annual report unless an amendment is needed for an error or a critical need.
Retail and wholesale are computed at 0.375 percent and businesses outside that pair at 0.75 percent, both of those rates living on the Comptroller's home page and traveling with the year the spreadsheet names, while the EZ computation is available when annualized total revenue is 20 million dollars or under for the entity or for the combined group at a rate of 0.331 percent, and choosing that computation gives up the margin deductions, with the long form required when revenue is over the no-tax threshold and EZ is not chosen or when a margin deduction will be taken.
May 15, the extension, and a late file
Put May 15 on the same calendar as the close, because that is the annual report's due day, and when May 15 lands on a weekend or a holiday the due day moves to the following business day, a shift you should read on the Comptroller's due-date page for the year in the spreadsheet rather than recycling last May from memory.
Extra time starts only if a payment, or the Comptroller's form, arrives by the original due day, and the payment that usually qualifies is the whole of last year's tax or ninety percent of what this year's report will show, except that a company which first came under this tax during the prior year cannot use the whole-of-last-year option on the first annual report it files.
Webfile or Form 05-164 is the path for a company that does not have to pay by electronic funds transfer, and that path's extended day is November 15, while a company that paid 10,000 dollars or more in the previous state fiscal year is on electronic funds transfer with a first extended day of August 15 and a further extension out to November 15, and a company at 500,000 dollars or more asks for the extension by a timely TEXNET payment under code 13080 without also sending Form 05-164, the clock time for that TEXNET payment being the one printed on the extensions page rather than a time copied onto this spreadsheet, and a final report comes due within 60 days after sufficient nexus ends, with a final-report extension of 45 days past that original final due day when the payment rules are met.
A late franchise report carries a 50 dollar penalty, franchise tax paid from day 1 through day 30 after the due day carries a 5 percent penalty on the tax, franchise tax paid after day 30 carries a 10 percent penalty on the tax, and interest begins on day 61, with the interest percent left unread on this page because it lives on the Comptroller interest page and it moves.
A sales-tax column beside the profit cell
Keep collected sales tax in its own spreadsheet column, apart from the franchise report and apart from profit, because the state piece is 6.25 percent, a city or a county or a transit district may add a local piece up to 2 percent, and the two pieces together stop at 8.25 percent on a single sale, with the local piece read from the Comptroller's locator on the day of the sale rather than memorized here as a city's number.
The letter that arrives after a permit is approved is what tells the spreadsheet whether the rhythm is monthly or quarterly, a monthly report leaving on day 20 of the following month, the April activity being the example that is due May 20, quarterly activity being reported in April and July and October and January, a yearly filer reporting the prior year on January 20, and a due day that falls on Saturday or Sunday or a holiday sliding to the next working day.
Until day 20, sales-tax cash sits in that column the way a draw and a loan already sit outside the profit cell, because typing the cash as sales would lift profit with money the shop was only holding, and a permitted seller who reports and pays on time may take a discount of one half of one percent of the tax, a prepaying seller may take that half percent plus a further 1.25 percent, a late sales-tax report carries a 50 dollar penalty, sales tax from day 1 through day 30 late carries 5 percent of the tax, sales tax after day 30 carries 10 percent of the tax, and interest on it begins on day 61 at whatever percent the interest page shows that day.
Gross revenue from goods and services into Texas over the prior 12 calendar months is the test, marketplace sales included even when the marketplace collected, and a remote seller under 500,000 dollars on that test is inside the safe harbor with no permit and no use-tax collection required, while a seller who uses only a marketplace and holds that marketplace's written statement in good faith also skips the permit and still keeps the records at least four years, and a person living in Texas who sells only through a marketplace still needs a permit because that seller has physical presence.
Marketplace sales belong in item 1 of the sales-tax return, the line for total Texas sales, and they come back out of item 2, the line for taxable sales, when the marketplace's written statement says the marketplace collected, remote sellers look up the single local use rate on Form 01-799 and this page leaves that percent unread because the Comptroller recomputes it, and Form 01-339 is the resale and exemption certificate a seller accepts, filled out, in place of tax on an item bought to be resold, the permit number never standing in for that filled-out certificate, the certificate kept four years, tax becoming due if the buyer later uses the item, and a buyer who is unsure of a resale not handing the certificate over.
The Comptroller letter after close
The feeling on this page is the letter. A Comptroller envelope on the counter after the shop is closed, naming a due date the spreadsheet cannot find. The workbook you already have is the one that should answer that envelope. A fresh blank cannot show whether May 15 was met, whether the sales-tax column was emptied on the 20th, or whether a loan got counted inside franchise revenue.
The hour is better spent on the row that makes the statement match, so the report can be read from that match, than on polishing a profit cell in the hope the envelope goes quiet, and a protest or a lawsuit that needs a lawyer stays with that lawyer, while an audit opinion, a review, or a compilation a bank wants signed stays with a firm allowed to sign it, those signed papers being different documents from the franchise report and from the sales-tax return.
Computing the margin from a matched spreadsheet, preparing the franchise report, and filing the information report are jobs this practice can do beside you, a paid preparer of a federal return still needs a preparer tax identification number for that federal return, and the person who keeps the columns is Steven Palmieri in the Tax CFO role the home page also calls the Entrepreneur's CFO, with the signing boundary drawn once on the disclosures page.
Bring the month that will not match, or say a Comptroller letter is already open. The call starts with the cleared column, before the profit cell, the same order we use for an owner in any other state. The Texas columns are the extra ones. The practice is the same practice.
The six column names, with no Texas amounts mixed in, live on the columns page. The form on this page is for the owner who wants the match kept, and who wants May 15 and the 20th written on the same calendar as the federal estimate vouchers in April, June, September, and January.
Here is a constructed example, labeled as one, so it is never mistaken for a filed return. A company whose revenue sits under the 2026 no-tax line of 2,650,000 dollars sends the information report and does not send the tax report. The file you send us is the one that has your rows in it.
Name the Texas month that will not match
You will be talking to the Steven Palmieri practice.